Researcher: Arosh De Silva
Course Instructor: Professor Zhenyu Cui
Introduction
Hedge fund investor letters describe managers’ views and how confidently they communicate them. This project explores whether a large language model can turn those cues into measurable features and whether the resulting signals relate to subsequent stock returns.
Methodology
The researcher extracted and cleaned text from investor letters issued by Greenlight Capital, Praetorian Capital, and Third Point. A large language model scored features including sentiment, conviction, uncertainty, complexity, unusual communication, and forward-looking tone. The project combined selected features into a behavioral signal and compared it with subsequent returns over multiple horizons.
Results & Analysis
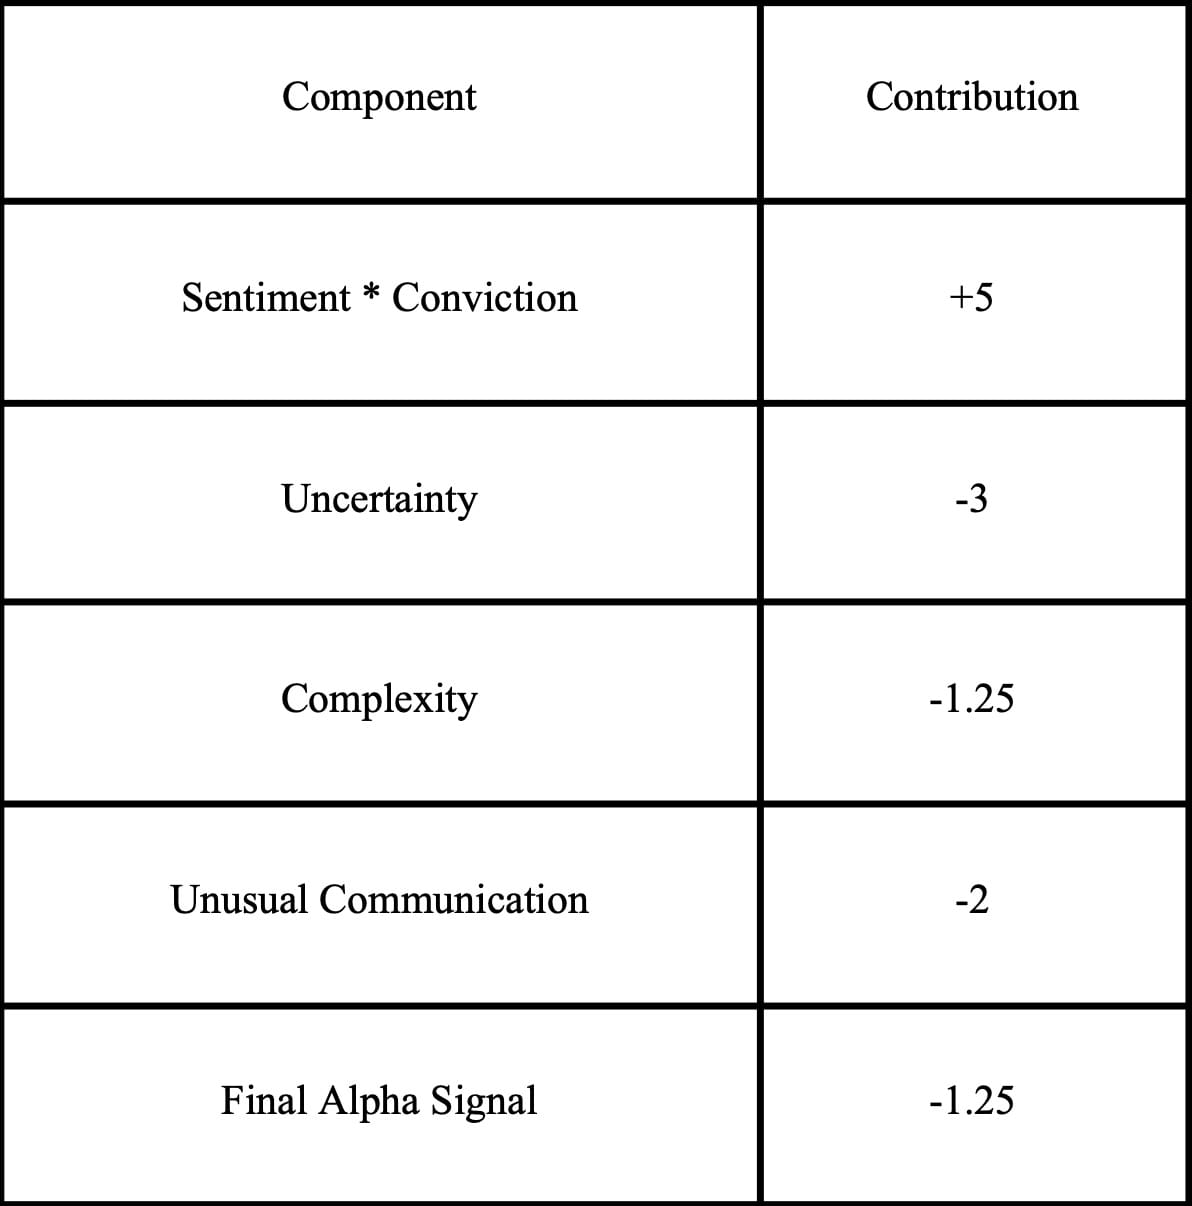
In several cases, bullish letters with elevated uncertainty, complexity, or unusual communication were followed by weaker short-term returns. The worked example illustrates how those features can change the interpretation of a letter with positive sentiment.
Conclusion
The project demonstrates how investor letters can be converted into structured features for return research. The small sample makes the findings exploratory, and a larger set of letters would help test whether the patterns hold across funds and market periods.