Researcher: Samuele Illiano
Course Instructor: Professor Zhenyu Cui
Introduction
Commercial real estate derives much of its value from future rental income and the eventual sale of the property. This project applies the fixed-income concepts of duration and convexity to measure how that value responds to changes in interest rates.
Methodology
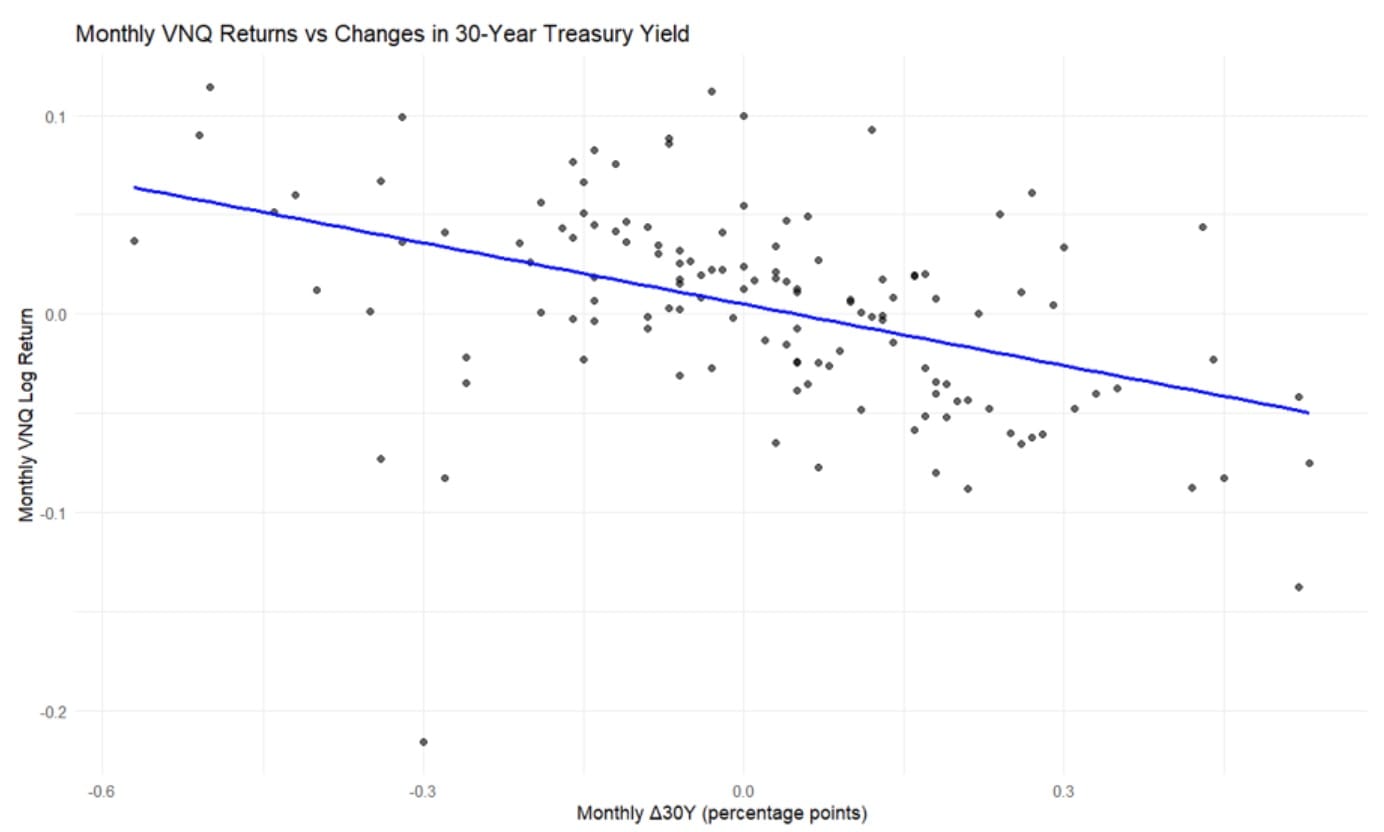
The researcher used the Vanguard Real Estate ETF (VNQ) as a market proxy and compared its daily and monthly returns with changes in 10-year and 30-year Treasury yields. A separate discounted cash flow model estimated property value from future net operating income and terminal sale value. The model was then used to estimate sensitivity to changes in the discount rate.
Results & Analysis
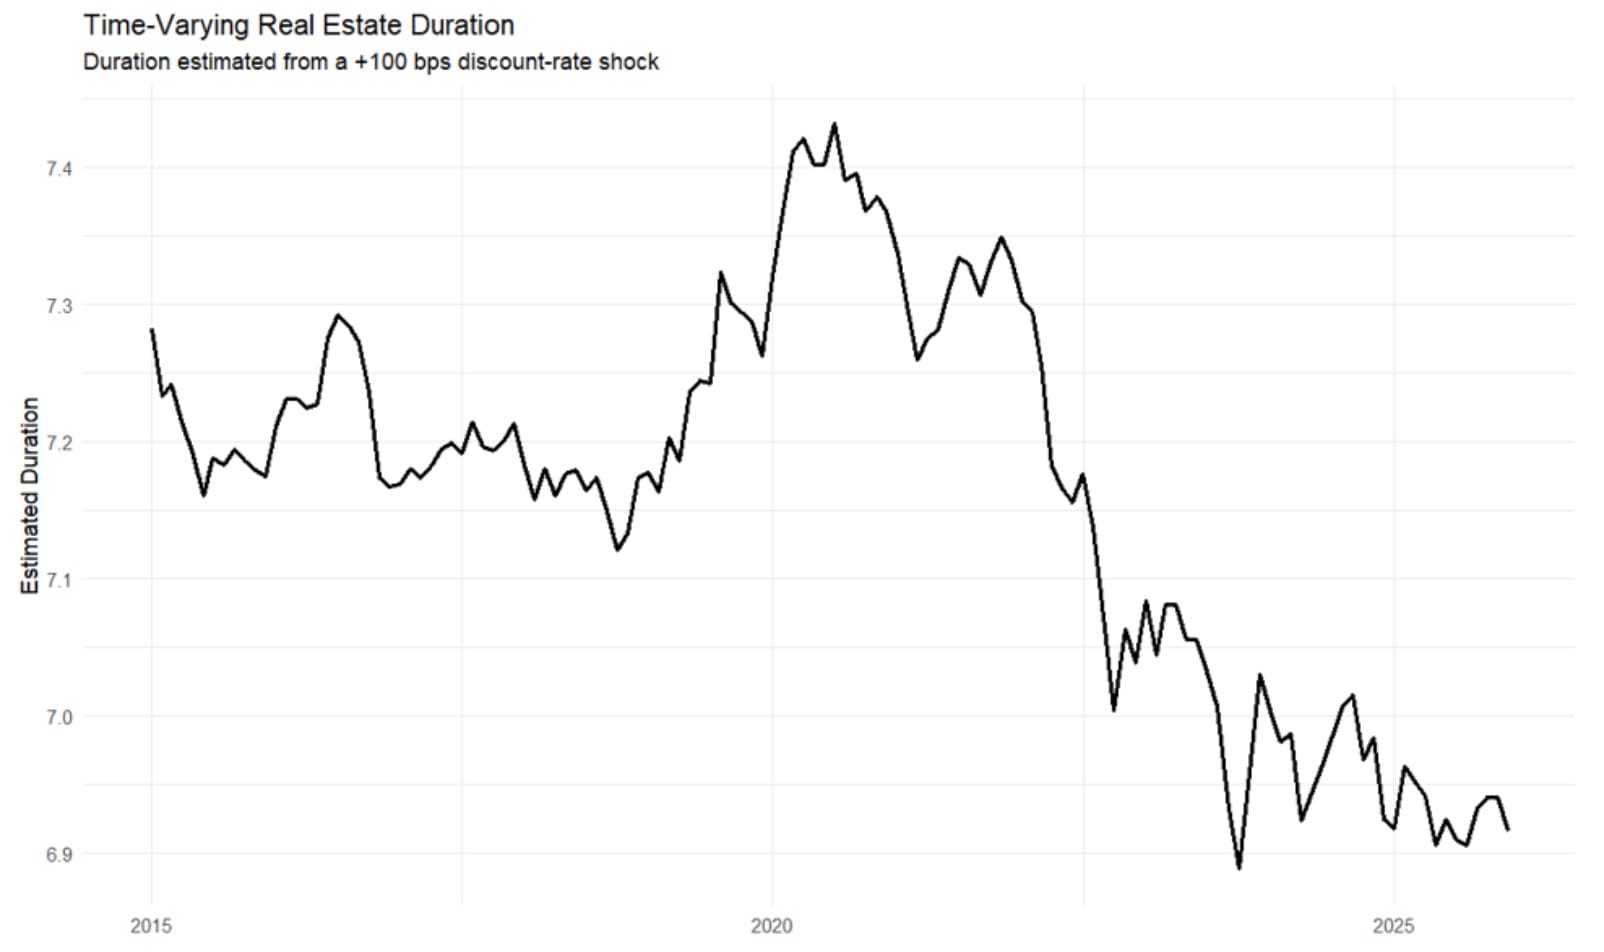
A 100-basis-point increase in the discount rate reduced modeled property value by about 7%, implying a duration of roughly 7.1. In the market data, the negative relationship was stronger at monthly frequency and more pronounced for changes in the 30-year yield than for changes in the 10-year yield.
Conclusion
The market regressions and the valuation model both point to sensitivity to long-term rates. The duration estimates also show how that sensitivity changes over time as valuation inputs change.