Researcher: Yizhou Xu
Introduction
Credit default swap prices provide a market-based measure of a firm’s credit risk. This project examines whether changes in that risk are associated with same-day equity returns for U.S. technology-related firms.
Methodology
The researcher estimated changes in implied hazard rates from Markit five-year senior unsecured credit default swap spreads and matched them with daily stock returns from CRSP. The final sample included 16 firms and 9,056 firm-day observations. The analysis compared credit risk shocks across firms and estimated each firm’s equity sensitivity.
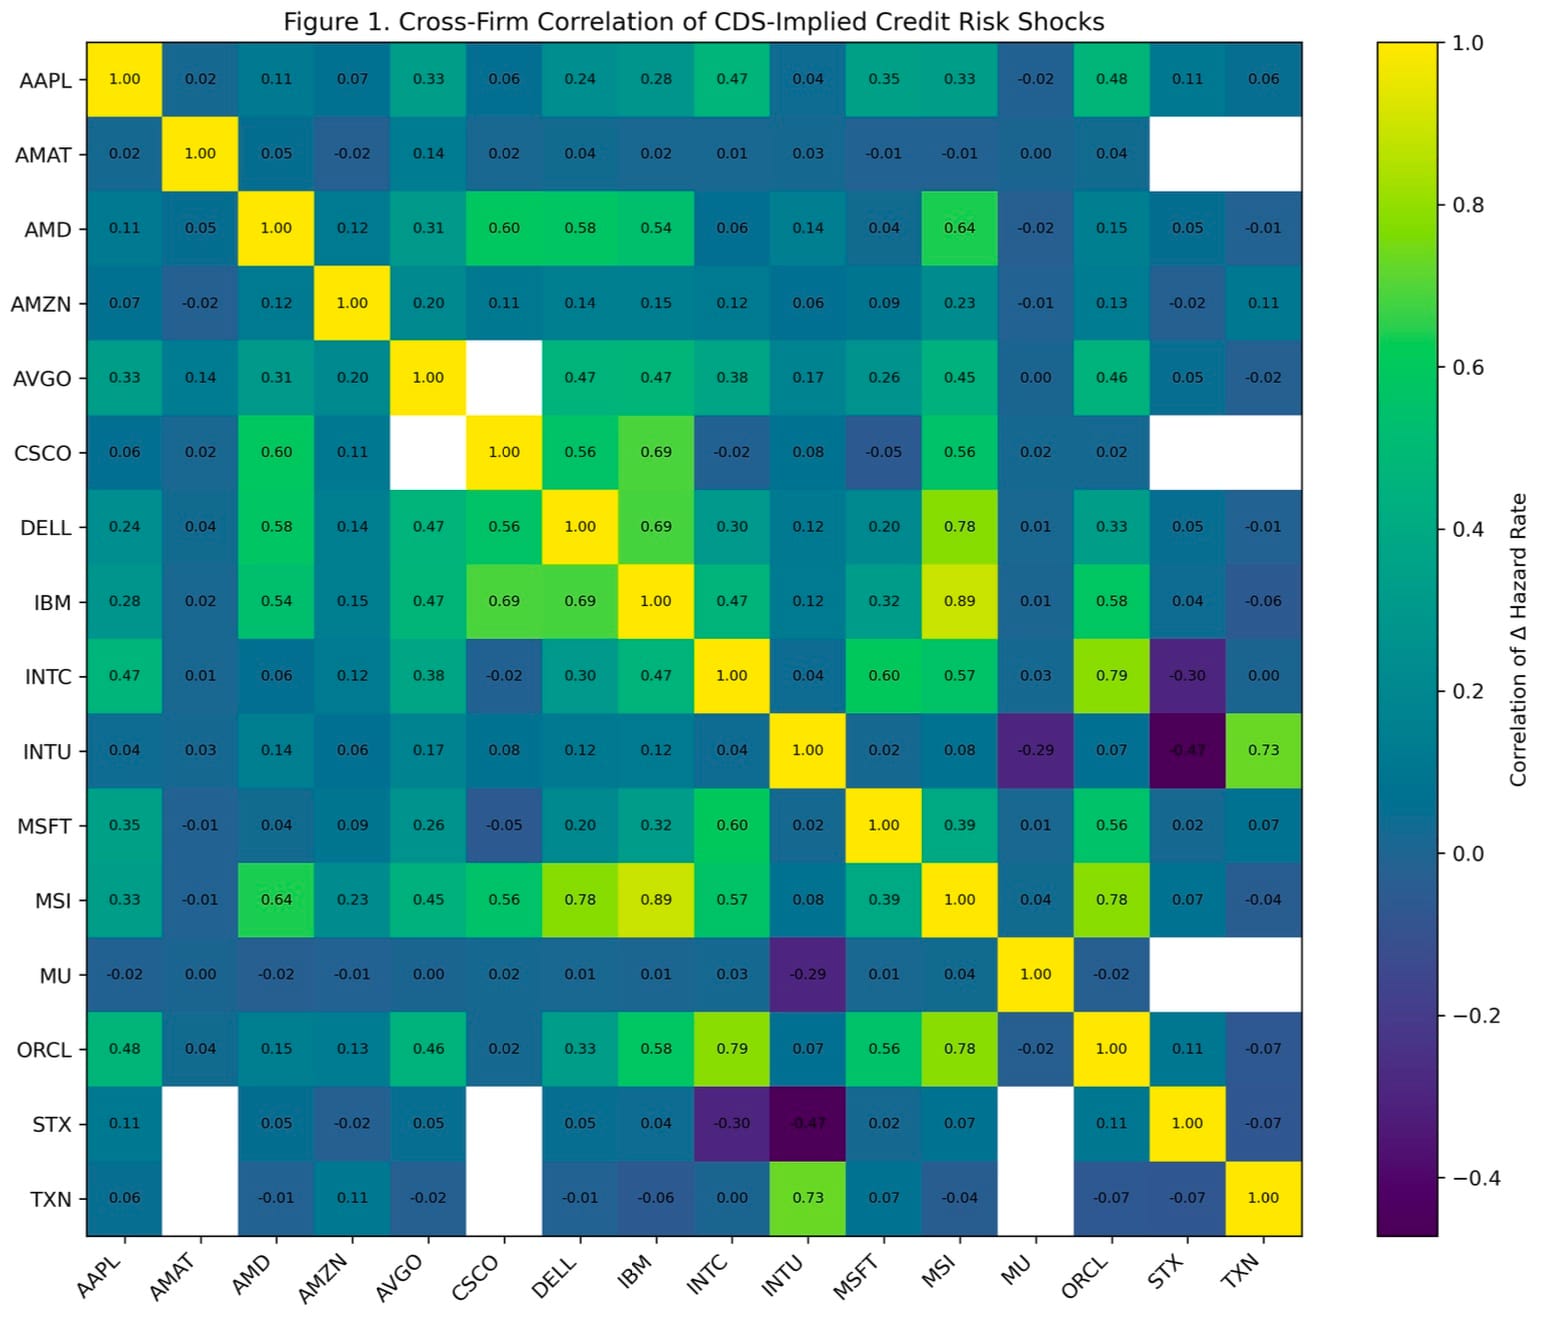
Results & Analysis
Fourteen of the 16 firms had negative equity sensitivity estimates, and six had negative estimates that were statistically significant at the 5% level. The size and precision of the estimates varied across firms. Cisco, AMD, and IBM, for example, had 95% confidence intervals entirely below zero.
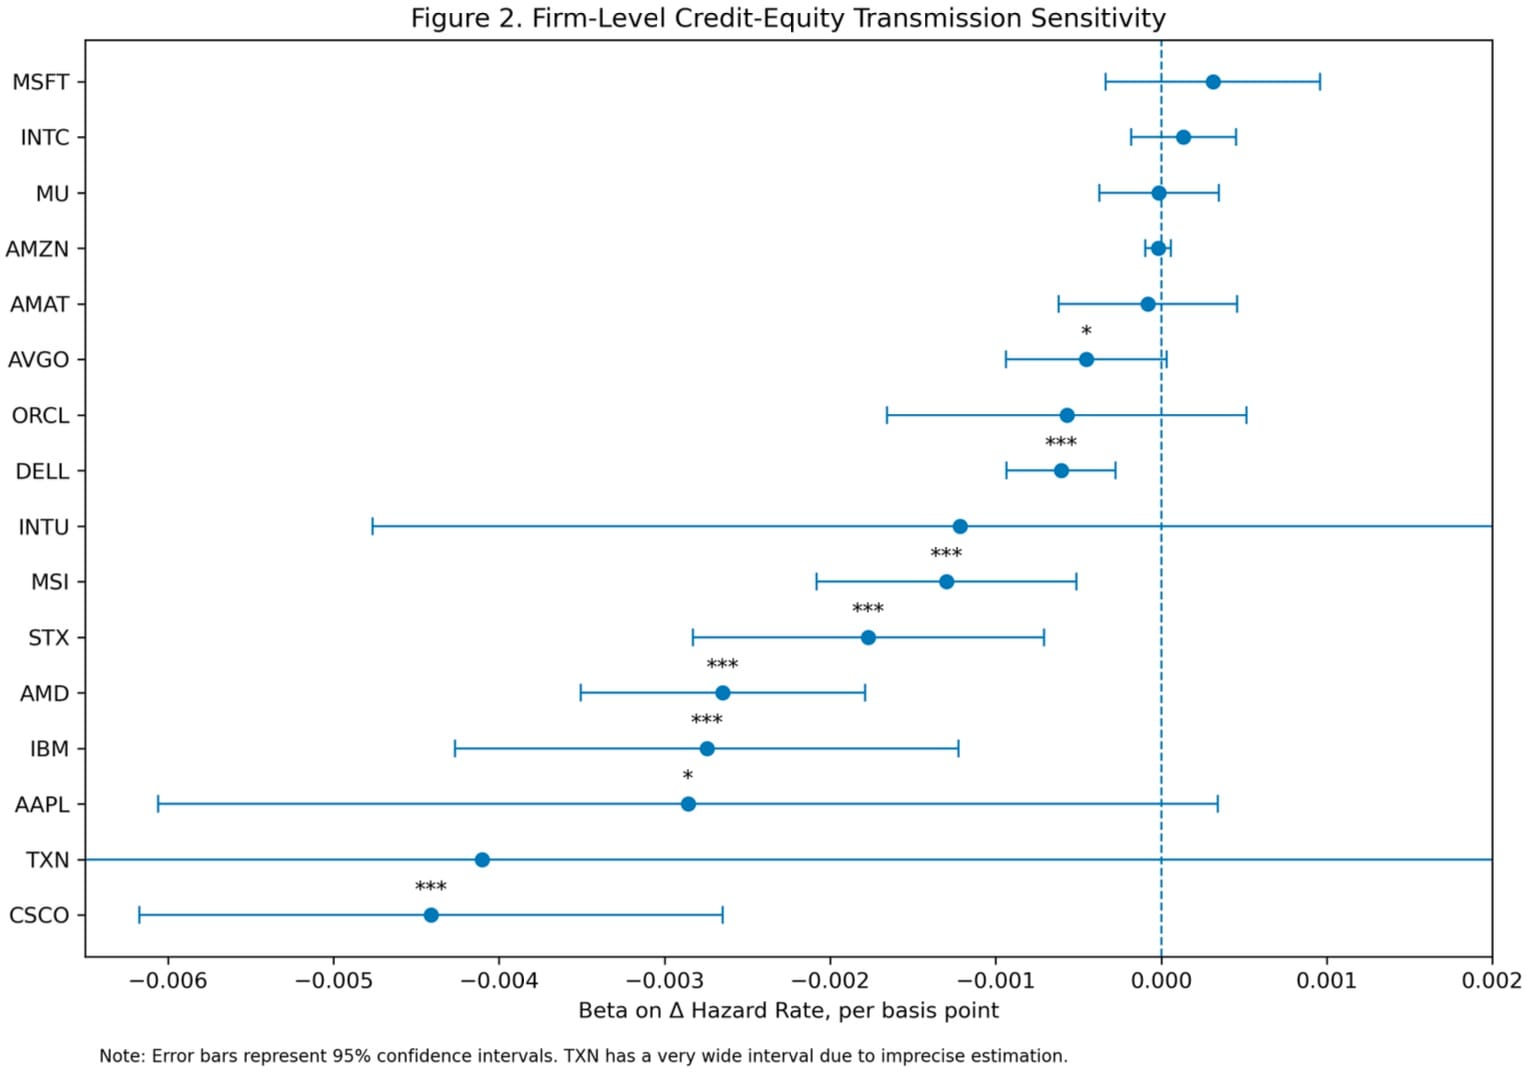
Conclusion
Rising implied credit risk was generally associated with weaker same-day equity returns in the sample. The variation in estimated sensitivities and their confidence intervals shows why firm-level results matter when assessing that relationship.