Researcher: Sharif Haason
Faculty Advisor: Dr. Ionut Florescu
Introduction
This project adapts the Implied Willow Tree (IWT), a method previously used primarily for equity options, to the 10-Year Treasury Note futures market. The adaptation accounts for how futures prices evolve and for the ability to exercise American-style options before expiration.
The research examines whether the adapted tree can model the risk-neutral dynamics of Treasury futures and reprice options across strikes and maturities.
Methodology
The study used Bloomberg options data across multiple maturities. It applied the Carr–Madan spanning formula to extract the mean, variance, skewness, and kurtosis of the risk-neutral distribution. A Johnson curve transformation mapped those moments into the tree. The calibration then adjusted node and transition probabilities to fit observed option prices while preserving a smooth distribution.
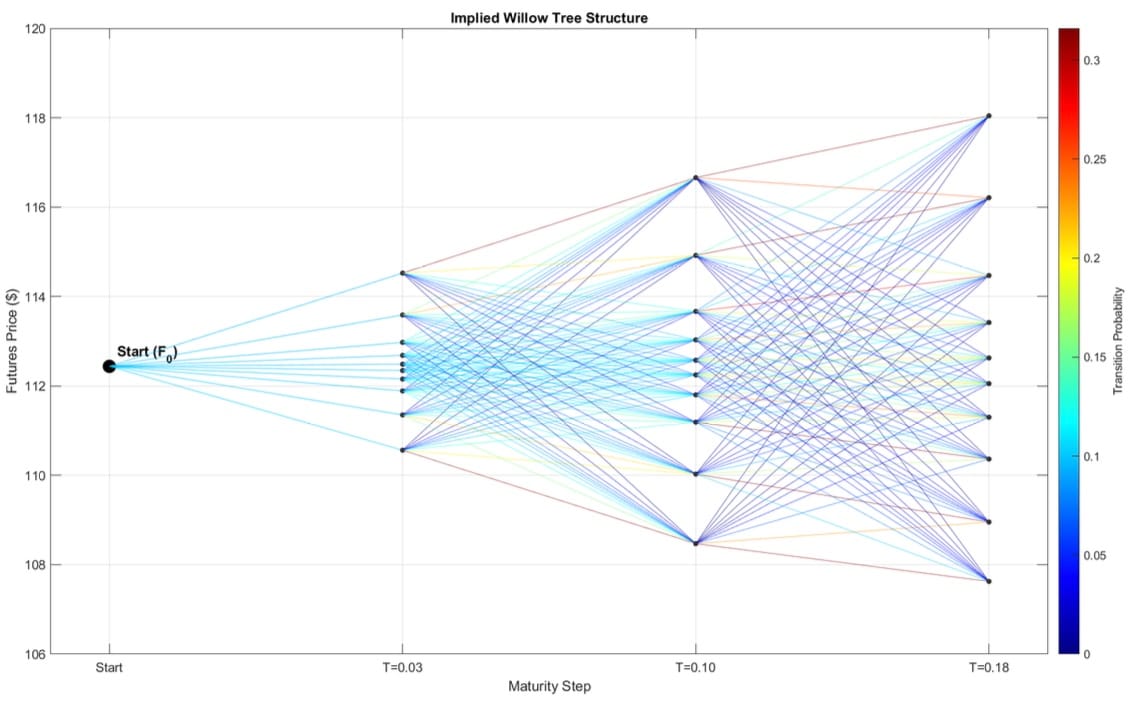
Read Figure 9 from left to right. The tree starts at the observed futures price and branches into possible price levels at three maturity steps. The color of each line represents the probability of moving between two price nodes. To price an American option, the model works backward from expiration and compares the value of exercising at a node with the value of keeping the option open.
Results & Analysis
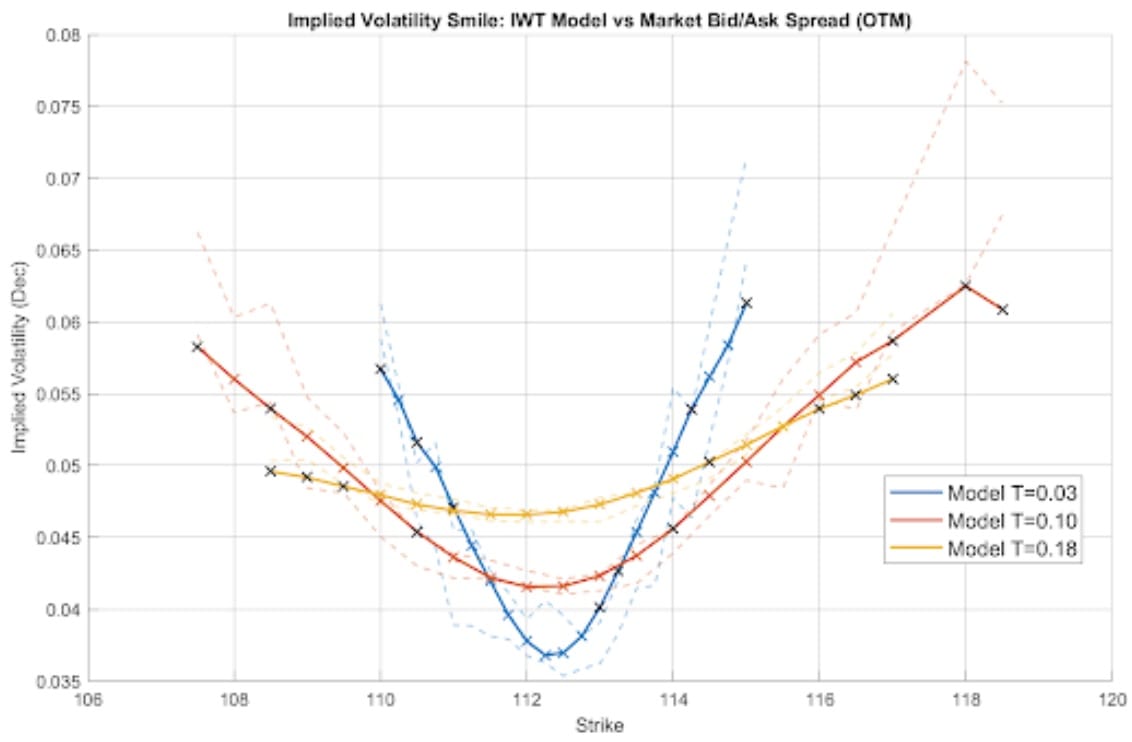
Most model prices fell within the quoted bid–ask spread, with the closest agreement near at-the-money strikes. Figure 5 shows the comparison in implied-volatility terms for out-of-the-money options. The solid curves show the model’s implied volatilities, and the dashed curves mark the market bid and ask bounds. Differences are generally more visible at strikes farther from the money.
The smoothing parameter affected the shape of the fitted distribution. Too little smoothing produced irregular distributions, while too much obscured the volatility skew. An intermediate setting gave the best balance in the calibration. The model also flagged one strike as a potential mispricing. That price difference provides a starting point for examining whether an opportunity could survive bid–ask costs and execution constraints.
Conclusion
The project shows how market quotes can be used to build a risk-neutral tree for Treasury futures that accommodates early exercise. By incorporating skewness and kurtosis into the futures price distribution, the framework offers a flexible approach to pricing American-style options and investigating discrepancies across strikes.